
Does a lower insurance estimate automatically mean your roof work is being shortchanged? Not always, but a difference deserves a careful review. If you’re deciding what to do when insurance underpays for roof replacement in Cedar Park, compare the work listed in each estimate, not just the final totals.
It’s understandable to worry that you’ll have to pay out of pocket for storm damage your policy may cover. Estimates can differ because of damage findings, measurements, the repair scope, or work that may not be covered. Heat, hail, and storms in Central Texas can also leave damage that needs clear photos and notes to assess.
This guide explains how to read the estimate, identify items that may be missing, and organize evidence for a follow-up. You’ll also learn how to review your policy and claim communications, then choose a practical next step, such as asking the insurer to reconsider documented items. A clear comparison helps you understand the gap without assuming every difference will be approved or paid.
Key Takeaways
- An estimate difference is a reason to compare details, not proof of an insurer error. Review roof areas, materials, quantities, and work descriptions side by side.
- To understand what to do when insurance underpays for roof replacement in Cedar Park, organize inspection findings and supporting photos around specific estimate items.
- Use a simple comparison table to identify unanswered questions and keep a clear record of insurer communications and applicable policy instructions.
- Choose a next step based on the evidence, such as requesting clarification or submitting additional documentation. Treat urgent leaks as a separate repair concern.
Why a Cedar Park roof replacement estimate may fall short in Austin, TX: What to do when insurance underpays for roof replacement in Cedar Park
A lower insurance estimate can feel like an underpayment, but a difference in scope or amount alone doesn’t prove the insurer made an error. The estimates may be based on different damage findings, measurements, materials, or listed work. To understand what to do when insurance underpays for roof replacement in Cedar Park, identify exactly where the documents differ.
An insurer’s estimate records the work and costs it recognizes for the claim; a roofer’s scope describes the repairs or replacement work identified during an inspection. Neither document, by itself, determines what the policy covers. General background on home insurance policies and claims can help explain the basic process, but your policy language and claim facts guide your specific coverage.
What can make two roof estimates look different?
Compare the same roof areas and listed tasks in both documents. One estimate may identify less damage, use different measurements, or assume different materials. It may also leave out work included in the roofer’s scope. Compare labor and quantities where both documents provide details, and mark questions instead of assuming either estimate is complete. Policy terms, exclusions, deductibles, and the facts of the loss can affect coverage.
Why Cedar Park storm documentation matters
Hail and storms can leave marks that are harder to assess later, so document what you can safely see from the ground. Take dated photos of visible changes and note when leaks or ceiling stains appear. Don’t climb onto a wet or damaged roof to take pictures. A roofer’s inspection can document visible roof damage and explain the proposed repair or replacement scope. For broader storm-damage documentation guidance, see our residential roofing information.
Steps for Underpaid Roof Claims in Cedar Park, TX
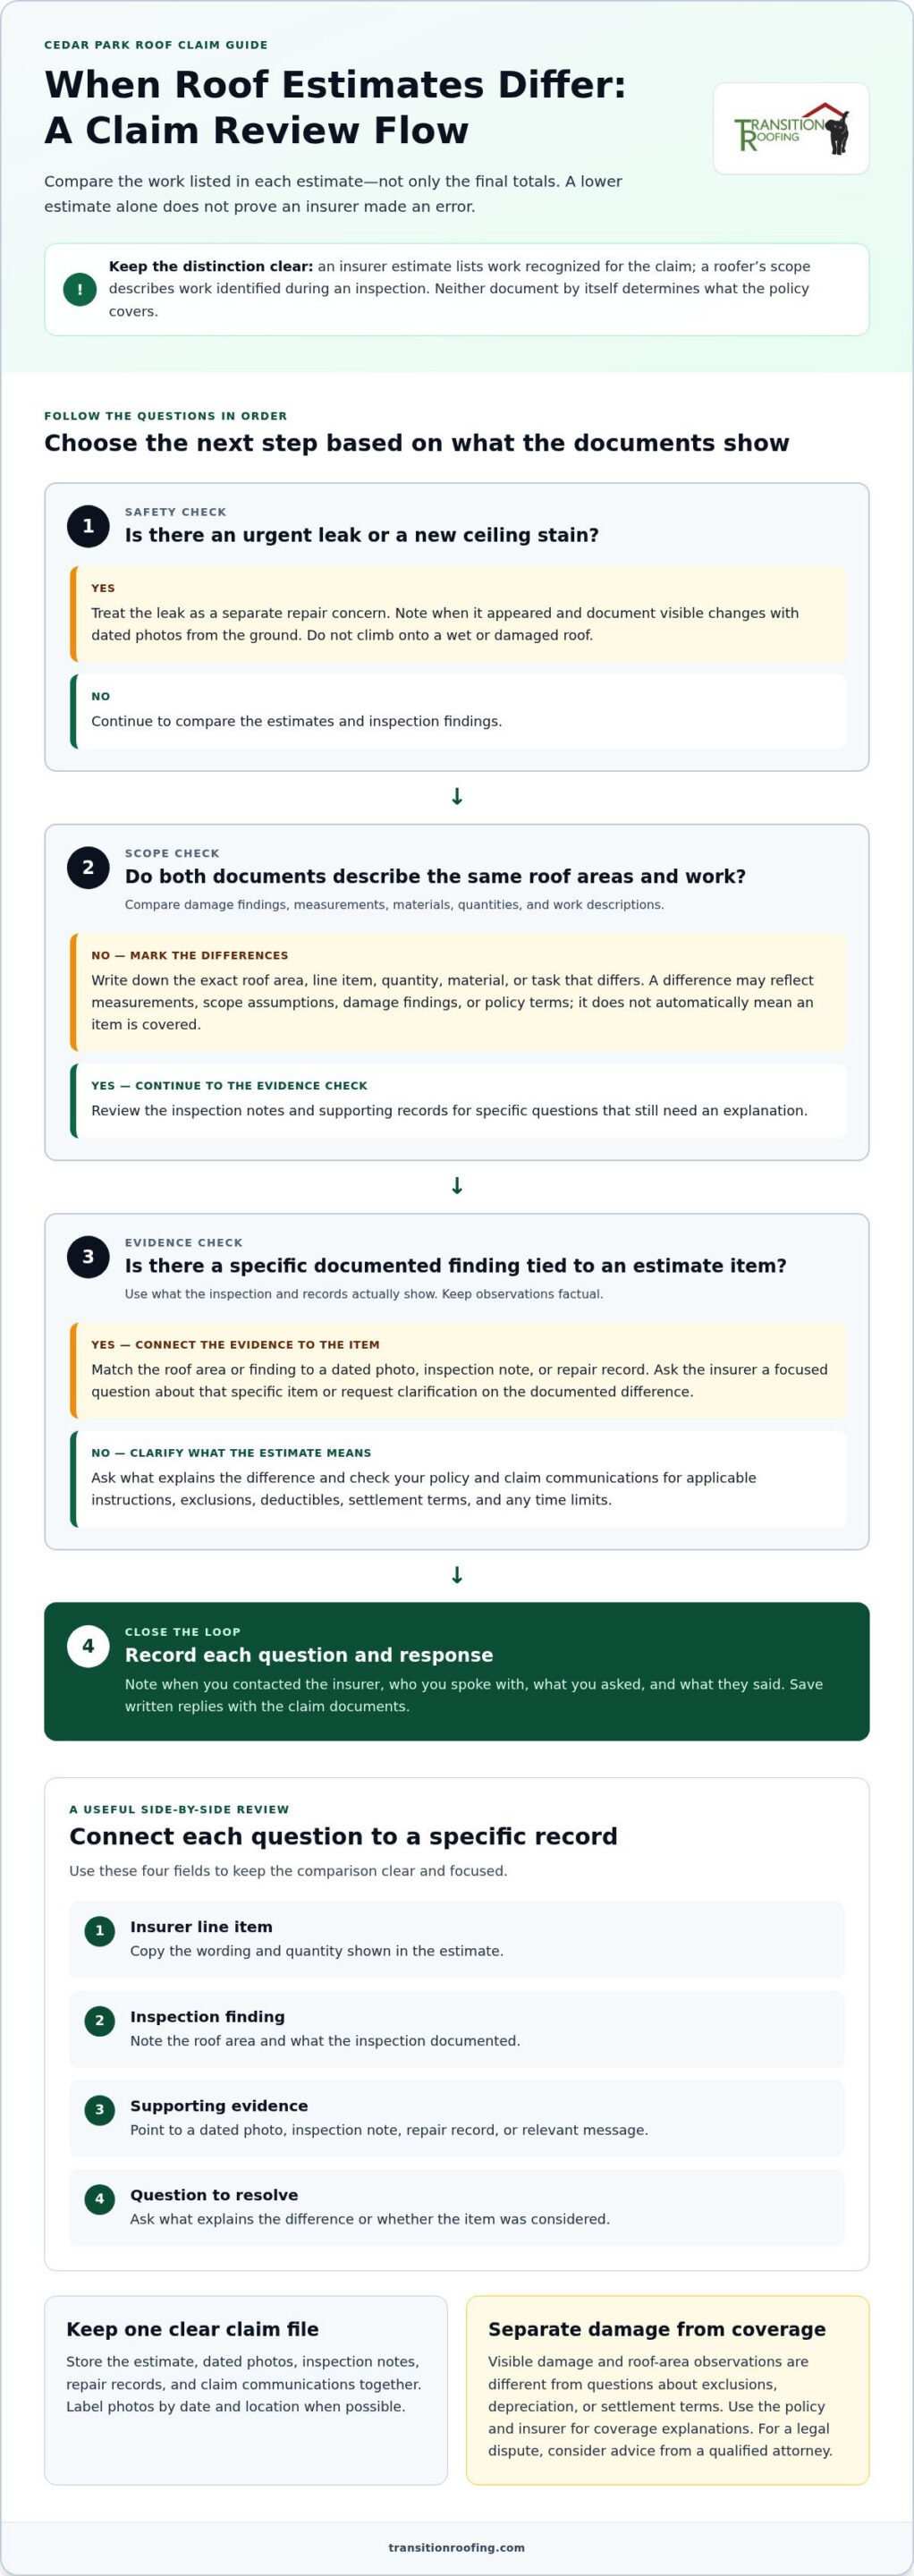
A clear process turns a broad disagreement into specific questions. If you’re deciding what to do when insurance underpays for roof replacement in Cedar Park, review the estimate and supporting documents in order. Check your policy and insurer communications for claim instructions and any time limits that apply.
- Read the insurer’s estimate. Note which roof areas, damage, materials, and tasks it includes, along with any items it says are excluded or not covered.
- Compare the scopes. Set the insurer’s estimate beside the roofer’s written inspection findings. Mark differences in areas, quantities, materials, or work descriptions. A roofer can document visible damage and explain proposed work, but can’t decide what the policy covers.
- Collect supporting evidence. Keep dated photos, inspection notes, repair records, and relevant messages together. Stick to what you observed, and don’t climb onto the roof or disturb damaged areas.
- Ask focused questions. Refer to specific estimate items. Ask for clarification about a roof area, quantity, material, or omitted task instead of making a general request for more payment.
- Track every response. Record when you contacted the insurer, who you spoke with, what you asked, and what they said. Save written replies with your claim documents.
Build a clear roof-damage file
Use one digital or paper folder for the estimate, dated photos, inspection notes, repair records, and claim communications. Label photos by date and location when possible. Keep your notes factual, such as where a leak appeared or what changed after a storm. An organized file makes it easier to connect evidence to a specific estimate item.
Ask the insurer focused questions
For example, ask how a listed quantity was measured or whether a particular roof area was included in the inspection. Keep your questions direct and factual. Transition Roofing provides insurance claim assistance and can help clarify inspection findings and the proposed work scope. If you need a Cedar Park roof inspection, we can review visible damage and provide a clear estimate for the work identified.
How Cedar Park homeowners can compare a roof scope in Austin, TX
A side-by-side review can show whether two estimates describe the same work. Comparing the scope is a practical first step in what to do when insurance underpays for roof replacement in Cedar Park. Compare details both documents provide, such as roof areas, material descriptions, work items, and quantities. A difference may come from measurements, scope assumptions, or policy terms. It doesn’t automatically mean an item is covered.
Connect each question to a specific observation or document. Use a simple four-column table:
- Insurer line item: Copy the wording and quantity from the estimate.
- Inspection finding: Note the roof area and what the inspection documented.
- Supporting evidence: Point to a dated photo, inspection note, or other relevant record.
- Question to resolve: Ask what explains the difference or whether the item was considered.
Separate missing damage from policy questions
Keep physical observations, such as visible damage or an identified roof area, separate from questions about exclusions, depreciation, or settlement terms. The insurer and your policy documents are the right sources for coverage explanations. If the disagreement involves legal rights or a legal dispute, consider advice from a qualified attorney.
When to request another review
Request written clarification when documented inspection findings don’t appear in the insurer’s scope. Refer to the exact item and attach the evidence that relates to it. A roofer can explain observed damage and proposed work, but cannot decide whether the policy covers it. For details about local residential services, visit our residential roofing page. Transition Roofing can inspect the roof and help compare its documented findings with the written scope.
Choosing the next step after an insurance roof underpayment in Cedar Park and Austin, TX
Choose your next step based on what the documents show. If the insurer’s estimate doesn’t address a documented roof condition, request clarification or submit the inspection notes and photos that support it. If the estimate and inspection describe different work, ask the roofer to explain the proposed repair or replacement scope. For questions about exclusions, settlement terms, or what the policy covers, contact the insurer and follow the instructions in your policy and claim communications.
A leaking roof may need attention before the estimate disagreement is resolved. Discuss practical leak mitigation or repairs with a roofing professional to help protect the home. Whether the insurer reimburses any work depends on the policy terms and claim facts, so don’t assume urgent repairs or additional documentation will result in payment.
When a roofing contractor can help clarify the scope
Transition Roofing can inspect a Cedar Park roof, document visible conditions, and explain the residential repair or replacement work identified. That technical review can make the scope clearer, but it doesn’t determine coverage or guarantee a claim outcome. For related local damage concerns, see our residential roofing information.
When the disagreement needs claim-specific advice
If you still have questions about how policy language applies, ask the insurer for a clear explanation. For a legal dispute or advice about your rights, speak with an appropriately qualified professional. A roofer can explain roof conditions and work, but can’t act as a public adjuster or decide whether the insurer should cover a loss.
If you’re still weighing what to do when insurance underpays for roof replacement in Cedar Park, Transition Roofing can inspect the roof and explain the documented scope. Request a roof inspection and clear next steps, with no assumption that additional insurance payment is guaranteed.
Move forward with a clear roof claim plan
A difference between an insurer’s estimate and a roofer’s scope is a reason to review the details, not proof that every disputed item is covered. Compare work descriptions and quantities, connect questions to inspection findings or dated photos, and keep a record of claim communications. For coverage questions, rely on your policy and the insurer’s explanation.
Knowing what to do when insurance underpays for roof replacement in Cedar Park starts with clear documentation. A roofer can inspect visible conditions and explain the repair or replacement work identified, but only the insurer can explain its coverage decision. If a leak needs attention, discuss practical repairs promptly while keeping reimbursement questions tied to your policy and claim facts.
Transition Roofing serves Cedar Park and Central Texas homeowners with residential roof replacement and insurance claim assistance. We also serve nearby communities including Austin, Round Rock, Pflugerville, Lakeway, Hays, Bear Creek, San Leanna, Rollingwood, West Lake Hills, Buda, Kyle, and Bee Cave. Schedule a Cedar Park roof inspection and get a clear plan.
Frequently Asked Questions
What should I do first if my insurance estimate is too low for roof replacement?
Read the estimate and compare its listed roof areas, materials, quantities, and work with the inspection findings. Mark specific differences, then check your policy and insurer communications for claim instructions and applicable time limits. If you’re deciding what to do when insurance underpays for roof replacement in Cedar Park, organize the evidence before asking the insurer to explain an omitted item or quantity.
Can a roofing contractor help if insurance underpays for roof replacement?
Yes. A roofing contractor can inspect visible conditions, document damage, and explain the repair or replacement work identified. That written scope can help you ask focused questions about differences in the estimates. A contractor can’t decide what your policy covers or guarantee that the insurer will approve additional work or payment. Coverage decisions depend on the policy and the facts of the claim.
What documents should I send when asking an insurer to review a roof estimate?
Send the estimate items you’re asking about with relevant dated photos, written inspection findings, and repair records if available. Identify the roof area and explain how each document relates to your question. Keep copies of what you submit and the insurer’s replies. Use factual notes about visible conditions, and don’t climb onto the roof or disturb damaged areas to collect evidence.
Does a higher roofing estimate mean insurance has underpaid?
No. A higher contractor estimate shows a difference in the proposed scope or amount, but it doesn’t prove that the insurer made an error or that every item is covered. Compare matching roof areas and work descriptions where both estimates provide details. Differences may involve measurements, material assumptions, policy terms, or claim facts. Ask for clarification on specific items rather than relying on totals alone.
What if the insurer still disagrees with my roof replacement estimate?
Ask the insurer to explain its position in writing and review your policy for any next steps or time limits. You may submit relevant additional documentation or seek qualified advice about unresolved coverage questions. If a leak needs attention, discuss repair options to help protect the home; reimbursement depends on the policy and claim facts. A roofing contractor can clarify roof conditions, not decide the coverage dispute.
If you’re dealing with a roof estimate that doesn’t match the documented damage, schedule a Cedar Park roof inspection and we can explain the findings and proposed work scope.